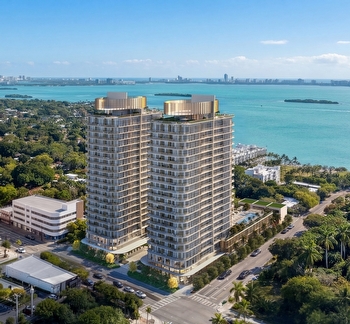
Miami Preconstruction Market Update: Luxury Tower Status for Late 2026
Miami’s luxury preconstruction market enters the final months of 2026 from a position of real strength, carrying the largest new development pipeline the region has ever seen. Across Miami Dade, Broward, and Palm Beach, more than two dozen branded and ultra luxury towers are actively selling or rising, representing well over 15 billion dollars in combined value. For buyers, sellers, and owners, understanding where these projects stand right now is essential, because the preconstruction market and the resale market have begun to move in strikingly different directions.
This update looks at the forces shaping demand this year and then walks through the current status of the marquee projects that define the top of the market. From the first supertall rising in Downtown to the branded wave transforming Brickell and the barrier island, these are the buildings setting the tone for Miami luxury in 2026 and beyond.
Preconstruction Has Separated From the Resale Market
The defining story of 2026 is that preconstruction and resale are now behaving as two distinct markets. On the resale side, the broader condominium market has softened into clear buyer territory, with roughly 17 months of supply across many neighborhoods. New preconstruction, by contrast, has continued to climb. Through the first half of the year, signed luxury preconstruction contracts cleared somewhere between 12 and 18 percent above initial release pricing, as developers raised their pricing tiers in response to steady absorption.
That gap matters. Buyers who judge a new tower by looking only at older resale comparisons are likely to misread the launch market, because preconstruction is now setting the price and resale is following. Reservation volume early in the year ran well ahead of the prior quarter and far ahead of the same period a year earlier, a sign that confidence at the top of the market remains intact even as the entry level cools.
The Branded Premium Is Real
One of the clearest themes of this cycle is the strength of branded residences. Towers carrying a hospitality or fashion name are outperforming unbranded product by roughly 11 to 18 percent on price per square foot, and the gap has proven durable rather than promotional. Names such as Waldorf Astoria, St. Regis, Cipriani, Baccarat, Aston Martin, Bentley, and Rosewood now anchor the Miami skyline, and buyers are paying measurably more for the service, design, and resale confidence that a respected brand provides.
The appeal rests on more than a logo. These buildings deliver hotel grade service, managed amenities, and a level of design discipline that holds value over time. In a market with so much new supply, the brand has become a way for buyers to identify quality quickly, and for owners to protect long term value.
What Is Driving Demand
The fundamentals behind Miami’s luxury demand remain firmly in place. Florida’s absence of a state income tax continues to attract high net worth households from higher tax states, and the year round climate keeps the region at the top of relocation lists. Foreign buyers remain highly active, drawn by the city’s deepening financial and cultural infrastructure and by the stability of United States real estate.
Perhaps the most important shift is that Miami is increasingly a primary home rather than a seasonal one. A growing share of ultra wealthy buyers are relocating permanently, which supports demand for larger residences, full service buildings, and the kind of turnkey living that branded towers are designed to deliver. Major global events on the calendar have added another layer of attention to the city, reinforcing its arrival as a true international capital.
Downtown Miami and the First Supertall
Nothing captures the moment more than the Waldorf Astoria Hotel and Residences rising at 300 Biscayne Boulevard. Designed as a stack of glass cubes climbing 100 stories to 1,049 feet, it is set to become Florida’s first supertall. The project began its ninth and final cube in late summer, reaching roughly the 85th level, and is expected to top out around the end of 2026 before completion in 2028. With nearly 400 private residences above a Waldorf Astoria hotel, the tower is reported to be more than 90 percent sold, a remarkable figure for a building of its scale and price.
The Waldorf has become a symbol of how far Downtown has come. Once a secondary address for luxury buyers, the urban core is now home to some of the most ambitious residential architecture in the country, and its skyline is being rewritten floor by floor.
Brickell Leads the Luxury Pipeline
Brickell remains the center of gravity for Miami’s branded wave. The headline this year belongs to Cipriani Residences at 1420 South Miami Avenue, which topped out in July 2026 at roughly 950 feet to become the tallest residential tower south of Manhattan. The 80 story building, the Cipriani brand’s first ground up residence in North America, holds 397 homes and had already passed 80 percent sold at the time it reached full height, with delivery anticipated in the summer of 2027.
Nearby, the St. Regis Residences on Brickell Avenue continues to perform at the very top of the market. The 50 story bayfront tower holds 152 residences and is well past 80 percent sold, and a recent penthouse contract near 47 million dollars ranked among the largest condominium transactions in Brickell history. Completion is targeted for late 2027. Along the river, Baccarat Residences has climbed well into its 75 story frame and is reported to be nearly sold out, with delivery expected in early 2028.
The pipeline runs even deeper. On Brickell Key, the Residences at Mandarin Oriental reset mainland pricing expectations with two penthouses trading near 50 million dollars each. The Residences at 1428 Brickell continue to rise toward a 2028 delivery, and a proposed Dolce and Gabbana tower at 888 Brickell has been designed to reach the same 1,049 foot height as the Waldorf, which would tie it as the tallest in the city once it moves forward.
Miami Beach and the Barrier Island
Across the bay, Miami Beach continues to attract boutique, design driven projects on some of the last prime oceanfront parcels. The Perigon, a collaboration anchored by world class architecture on the sand, commands pricing that starts in the double digit millions and has progressed steadily through construction. Five Park, at the gateway to South Beach, has reshaped the southern skyline with its tower and surrounding park.
Further north, the Shore Club Private Collection is advancing through construction on its historic oceanfront site, and Aman Residences is bringing one of the most revered names in hospitality to the island. These projects share a common thread. They are intentionally small, deeply amenitized, and positioned for buyers who want privacy and brand pedigree in equal measure.
Sunny Isles, Bal Harbour, and Fisher Island
The northern beaches remain a stronghold for oceanfront branded living. In Sunny Isles Beach, Bentley Residences continues to advance toward a 2028 delivery with its signature in unit car elevators, while the St. Regis Residences there moves forward on a two tower plan, with the second tower breaking ground late in 2026 and completion expected in 2028. On Fisher Island, one of the most exclusive zip codes in the country, the newest collection of residences has entered its final stages, offering a rare chance to own on the private island.
These markets rarely see large volumes of new supply, which is precisely why demand holds so firmly. Limited inventory, high barriers to entry, and established prestige keep values resilient even when the broader market cools.
Edgewater and the Emerging Corridors
Edgewater has matured into one of the most watched corridors in the city, prized for its bayfront position between Downtown and the Design District. Villa Miami has become a defining project for the neighborhood at the ultra luxury tier, and additional branded and design led towers continue to launch along the waterfront. For buyers seeking new construction with strong value fundamentals and genuine upside, these emerging corridors deserve close attention alongside the established luxury enclaves.
What This Means for Buyers and Owners
For buyers, the message of late 2026 is to evaluate preconstruction on its own terms. Well positioned branded towers in strong submarkets have continued to appreciate through their construction periods, and the best inventory, pricing, and incentives tend to go early. Entering at a thoughtful release tier, in a project backed by a proven developer, remains one of the most compelling ways to participate in the Miami market.
For current owners, the divergence between preconstruction and resale is a reminder to price and position carefully. Older stock is being repriced against a wave of new product that offers modern design, hotel grade service, and brand assurance. Understanding exactly where a specific building sits within that landscape is the difference between a confident decision and a costly guess.
Work With a Miami Luxury Specialist
Miami’s luxury market has never been deeper or more nuanced, and the right guidance has never mattered more. Whether you are considering a preconstruction purchase, weighing a sale, or simply trying to understand how these landmark towers affect the value of your home, working with an experienced local advisor ensures a clear and well informed decision. To discuss current availability, pricing, and strategy across Miami’s finest new developments, reach out today and start the conversation.
Explore Miami Beach Luxury Real Estate
From private island estates on Star Island and the Venetian Islands to oceanfront penthouses and new pre-construction developments, Lisa Cohn offers unmatched access to Miami Beach’s finest properties.
Ready to Find Your Miami Beach Property?
Lisa Cohn offers unmatched expertise, access to off-market listings, and personalized service for buyers and sellers of Miami Beach’s finest properties — with more than 25 years of experience and over $700 million in luxury sales.
(305) 927-1462 · lisa@lisacohn.net
1111 Lincoln Rd, Suite 805 — Miami Beach, FL 33139